Caregiver Blog
Budgeting When Income Drops Caregiving: 5 Powerful Ways to Regain Control

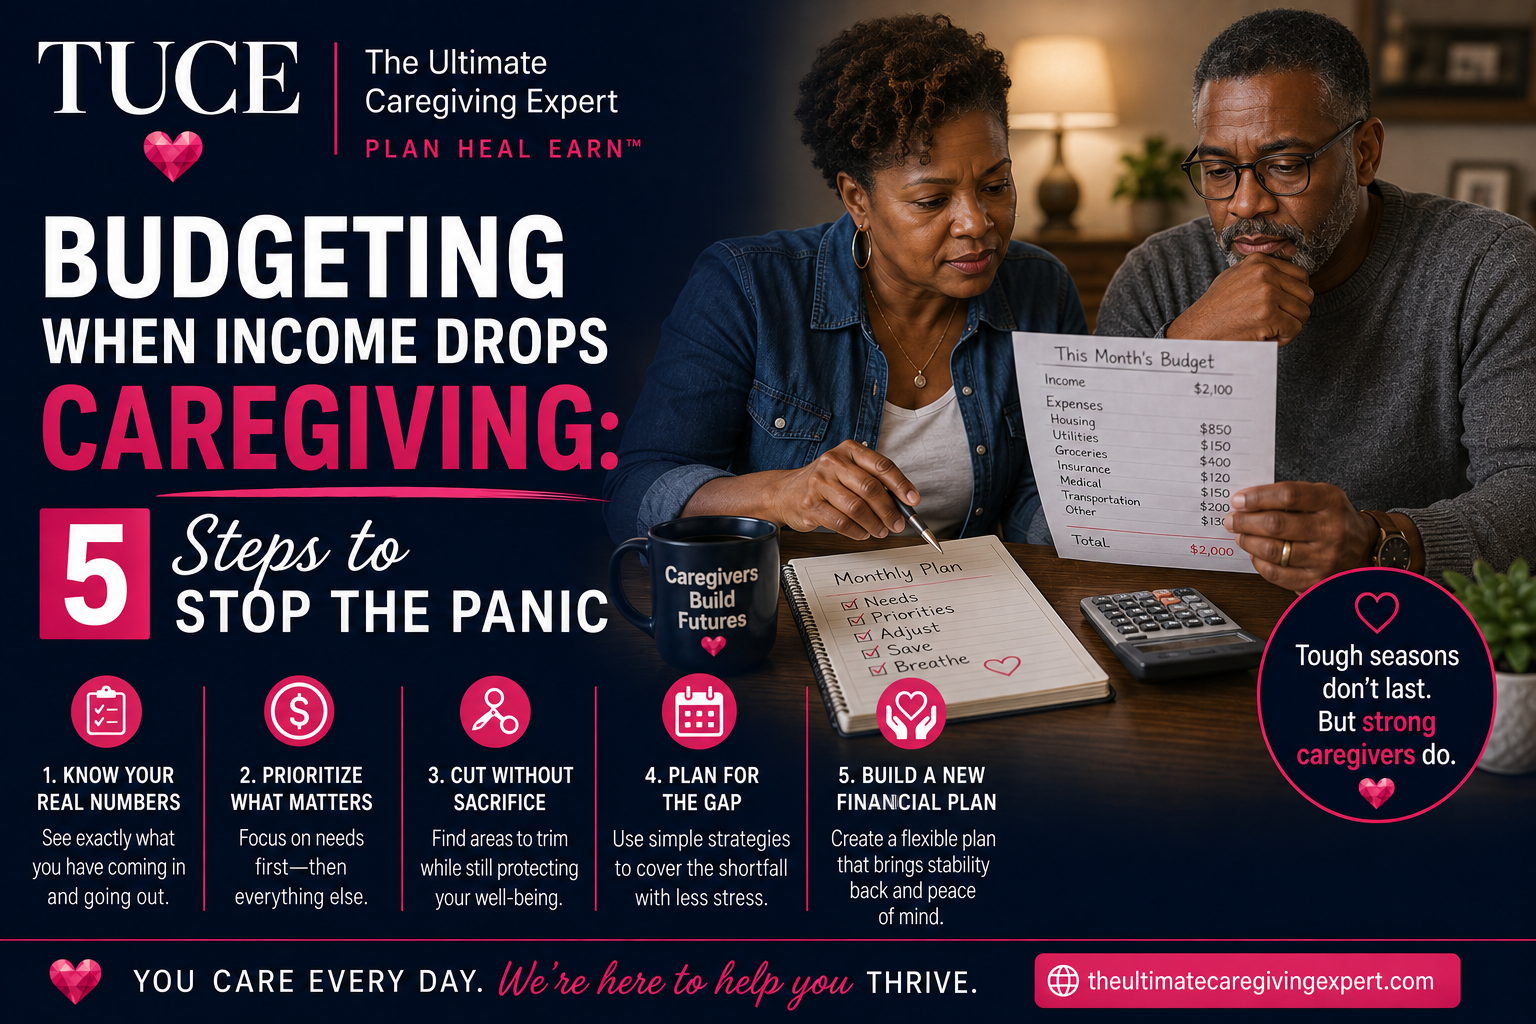
Budgeting When Income Drops Caregiving: 5 Powerful Ways to Regain Control
How to rebuild your budget around a smaller income, protect what you have, and create a financial plan that works with your caregiving responsibilities
Budgeting when income drops caregiving can be one of the hardest financial adjustments a family has to make. It often happens without warning. A paycheck becomes smaller, work hours are reduced, or someone has to step away from work to provide more care.
Suddenly, the budget that worked six months ago no longer matches the household’s reality.
This is where budgeting when income drops caregiving becomes more than a simple exercise in cutting expenses. You are not just changing numbers on a spreadsheet. You are adjusting your household finances around a major change in time, responsibilities, income, and priorities.
The good news is that a reduced income does not automatically mean financial disaster. Budgeting when income drops caregiving can help you understand what changed, identify what can be adjusted, protect important savings, and find available sources of assistance.
In this post, we will walk through five practical ways to rebuild your finances after a caregiving related income drop.
1. Understand What Changed Before You Cut Anything
The first step in budgeting when income drops caregiving is understanding exactly how much your household income has changed.
Do not start by immediately canceling subscriptions, cutting groceries, or moving money between accounts. Start with the numbers.
Write down your current monthly household income and compare it with what you were bringing in before caregiving changed your work situation.
Look at:
• Current take home income
• Previous take home income
• Reduced work hours
• Missed shifts
• Changes in overtime
• Lost freelance or side income
• New caregiving expenses
• Changes in transportation costs
• Changes in medical or household expenses
The goal is to identify the actual monthly gap.
For example, if your household previously brought in $5,000 each month and now brings in $3,800, the difference is $1,200.
That number may feel frightening at first, but knowing the exact gap gives you something concrete to work with.
You cannot rebuild a budget around a number you have not identified.
This is also where caregiver financial planning becomes important. The goal is not simply to spend less. It is to understand how caregiving has changed the entire financial picture.
Find Your New Monthly Number
When budgeting when income drops caregiving, use the income you can realistically expect now rather than the income you hope will return later.
If your work hours have been reduced, build the first version of your budget around the reduced amount.
If your income changes from month to month, consider using a conservative monthly estimate rather than your best month.
This creates a more realistic starting point.
2. Rebuild the Budget Around Your New Income
Once you know the size of the income change, rebuild the budget around your current reality.
Do not keep using the old budget and simply hope you can somehow stretch it further.
That approach often creates more stress because the numbers were built for a financial situation that no longer exists.
Instead, separate your expenses into three groups.
Essential Expenses
These are the expenses that keep your household functioning.
Examples include:
• Housing
• Utilities
• Insurance
• Groceries
• Transportation
• Minimum debt payments
• Required medical expenses
• Essential caregiving expenses
Adjustable Expenses
These are expenses that may be reduced without immediately affecting your household’s basic needs.
Examples include:
• Subscriptions
• Entertainment
• Dining out
• Nonessential shopping
• Certain memberships
• Optional services
Expenses That Can Be Delayed
Some purchases may not need to happen immediately.
This could include replacing nonessential items, upgrading technology, taking a planned trip, or making other purchases that can safely wait.
This three part approach makes budgeting when income drops caregiving easier because you are not treating every expense as equally important.
The question becomes:
What must be paid now, what can be reduced, and what can wait?
That is a much more useful question than simply asking where you can cut money.
Build Around Reality, Not the Old Budget
A major part of budgeting when income drops caregiving is accepting that your previous spending plan may no longer work.
That does not mean you have failed.
It means your circumstances changed.
Your new budget needs to reflect the life you are actually living today.
3. Build a One Week Caregiving Budget Before Planning the Whole Year
When income has recently dropped, planning an entire year can feel impossible.
Start with one week.
Track every dollar that comes into the household and every dollar that leaves it.
Do not rely on memory.
Write down groceries, transportation, medications, household purchases, caregiving expenses, subscriptions, meals, and small purchases that might normally seem insignificant.
At the end of the week, look at where your money actually went.
This gives you real information instead of assumptions.
A one week review can reveal expenses that were easy to overlook when your income was higher. It can also show where caregiving has created new costs that were not part of your previous budget.
For many families, budgeting when income drops caregiving becomes easier once they stop trying to predict everything and start working from real numbers.
After the first week, repeat the process for another week.
Then compare the two.
You may begin to see patterns.
Perhaps transportation is higher because of medical appointments. Maybe grocery spending has increased because another person is now living in the household. Perhaps work related costs have decreased because you are working fewer hours.
These details matter because your new budget needs to reflect the life you are actually living.
Turn One Week Into a Monthly Plan
Once you understand your weekly spending, you can begin creating a monthly caregiving budget.
Do not assume that every week will look exactly the same.
Instead, identify predictable expenses and irregular expenses.
This gives you a clearer picture of what your household needs each month.
That information becomes especially valuable when budgeting when income drops caregiving because caregiving expenses can change from one month to another.
4. Look for Programs That Can Reduce the Financial Pressure
Reducing expenses is only one side of the equation.
The other side is finding assistance that may reduce some of the financial pressure.
Depending on your household circumstances, you may want to research:
• SNAP benefits
• Utility assistance programs
• Local emergency assistance
• Community action programs
• Food assistance programs
• Housing assistance
• Caregiver support programs
• Medicaid related caregiver programs
• Veteran benefits when applicable
• Local nonprofit resources
Eligibility varies based on the program and your circumstances, so do not assume that you qualify or do not qualify based on someone else’s experience.
An income reduction can change your eligibility for certain programs, which means something that was unavailable to your household previously may be worth investigating now.
The official SNAP eligibility information is a useful starting point for understanding current requirements.
Local nonprofit organizations and community agencies may also have emergency resources for food, utilities, transportation, or other essential needs.
This is an important part of budgeting when income drops caregiving because sometimes the answer is not another expense cut.
Sometimes the answer is finding assistance that reduces an existing expense.
Research Assistance After an Income Change
When budgeting when income drops caregiving, do not only research programs based on your old financial situation.
Your household may now have different income, expenses, and caregiving responsibilities.
That change may affect which resources are worth investigating.
If caregiving has also created a major reduction in household income, it may be worth researching whether your state has a family caregiver compensation program or another form of support.
Our guide on family caregiver compensation programs by state can also help you understand where to begin your research.
5. Protect Your Savings and Future Financial Stability
When income drops, savings can start to feel like the easiest solution.
You may think:
“I will just use my emergency fund until things improve.”
That can be reasonable if you have savings available, but it is important to know exactly how quickly that money is being used.
Calculate your monthly shortfall.
Then estimate how long your current savings could cover that gap.
For example, if your household is short $500 each month and you have $5,000 available in emergency savings, the savings could theoretically cover ten months of that gap before considering other changes or unexpected expenses.
That calculation gives you a clearer picture of how much time you have.
It also tells you when you need to make another adjustment.
Be Careful With Retirement Accounts
Under serious financial pressure, retirement accounts can look like an emergency fund.
Before withdrawing retirement savings, consider the potential tax consequences, penalties, and long term impact.
If you believe a retirement withdrawal may become necessary, speak with your plan administrator or a qualified financial professional about the rules that apply to your specific account.
Do not assume that every withdrawal will have the same consequences.
Protect Your Emergency Savings
If you have emergency savings, avoid treating it as extra spending money.
Give every withdrawal a purpose.
Ask:
Is this expense essential?
Is there another way to cover it?
Will paying this expense now prevent a larger problem later?
These questions can help you use your savings strategically rather than watching the account slowly disappear without a plan.
This is one of the most important parts of budgeting when income drops caregiving because your savings may need to support your household for longer than expected.
What to Do When the New Budget Still Does Not Balance
Sometimes you can cut every reasonable expense and still have a gap.
That does not mean you failed.
It means the income reduction is larger than the expenses you can realistically eliminate.
This is an important part of budgeting when income drops caregiving that many families overlook.
There are only two basic sides of a household budget:
Money coming in.
Money going out.
If the second number cannot realistically become much smaller, the next question is whether the first number can increase.
That might mean:
• Taking on flexible work when caregiving allows
• Selling unused household items
• Exploring a small service based income stream
• Reviewing available caregiver benefits
• Asking whether work hours can be adjusted differently
• Exploring whether another household member can contribute
• Researching community assistance
The goal is not to tell a caregiver to simply work more.
Caregiving may make traditional employment difficult or impossible.
The goal is to look at the entire financial picture and identify every realistic option available to your household.
Have an Honest Conversation With Your Household
If other people share your household, do not carry the entire financial adjustment alone.
A spouse, partner, older child, or other household member may be able to contribute ideas, adjust spending, or take responsibility for specific expenses.
The conversation does not need to involve every private financial detail.
It simply needs to make the new reality clear.
You might say:
“Our income has changed because of caregiving, so our old budget no longer works. I want us to look at what needs to change before this becomes a bigger problem.”
That is very different from waiting until the household is already facing a financial emergency.
When everyone understands what changed, the budget becomes a household responsibility rather than something one person has to manage alone.
This can make budgeting when income drops caregiving feel less isolating because the financial adjustment becomes something the household can work through together.
What Your Budget Can Look Like Six Months From Now
The first few weeks after an income reduction can feel chaotic.
You may be constantly checking the bank account, worrying about upcoming bills, and wondering whether you made the right caregiving decision.
But a new financial routine can eventually make the situation feel more manageable.
After several months, you may have:
• A realistic monthly budget
• A clear understanding of essential expenses
• A smaller list of unnecessary expenses
• A weekly spending review
• A plan for emergency savings
• A better understanding of available assistance
• A strategy for handling irregular caregiving costs
This is the point where budgeting when income drops caregiving can stop feeling like a constant emergency and start becoming a financial system.
The situation may still be difficult.
Your income may still be lower.
Caregiving may still be demanding.
But you are no longer reacting to every expense without a plan.
You have numbers.
You have priorities.
You have a process.
And that can make a significant difference.
The Most Important First Step
If you are overwhelmed by the financial changes caregiving has created, do not try to solve everything today.
Start with one number.
What is your actual monthly household income right now?
Then identify your essential monthly expenses.
Then calculate the difference.
That number gives you the starting point for budgeting when income drops caregiving.
Once you know the gap, you can decide what needs to change, what assistance may be available, what expenses can be reduced, and whether you need another source of income.
The goal is not to create a perfect budget.
The goal is to create a budget that reflects your life now.
Where to Go From Here
If rebuilding your finances after an income reduction feels overwhelming, the Caregiver Cashflow Plan provides a structured way to work through your income, expenses, priorities, and financial options.
You do not have to figure out every financial decision at once.
Start with the numbers you know.
Identify the gap.
Protect what you can.
Look for available support.
Then build from there.
Free guide, I Am More Than a Caregiver: https://caregivingexpert.gumroad.com/l/Morethanacaregiver
The Caregiver Cashflow Plan, $27: https://caregivingexpert.gumroad.com/l/cashflow
The Caregiver Stability Snapshot, $197: https://theultimatecaregivingexpert.com/caregiver-stability-snapshot/
The Caregiver Stability Plan, $500: https://theultimatecaregivingexpert.com/caregiver-stability-plan/
The math changing is not a personal failure.
Caregiving can change household income, expenses, time, and priorities all at once.
Budgeting when income drops caregiving is about responding to that change honestly instead of pretending the old numbers still work.
One real week of information can become a new monthly plan.
One monthly plan can become a more stable routine.
And one realistic financial decision at a time can help you regain control.