Caregiver Blog
Budgeting for Caregivers: A Simple Monthly Plan

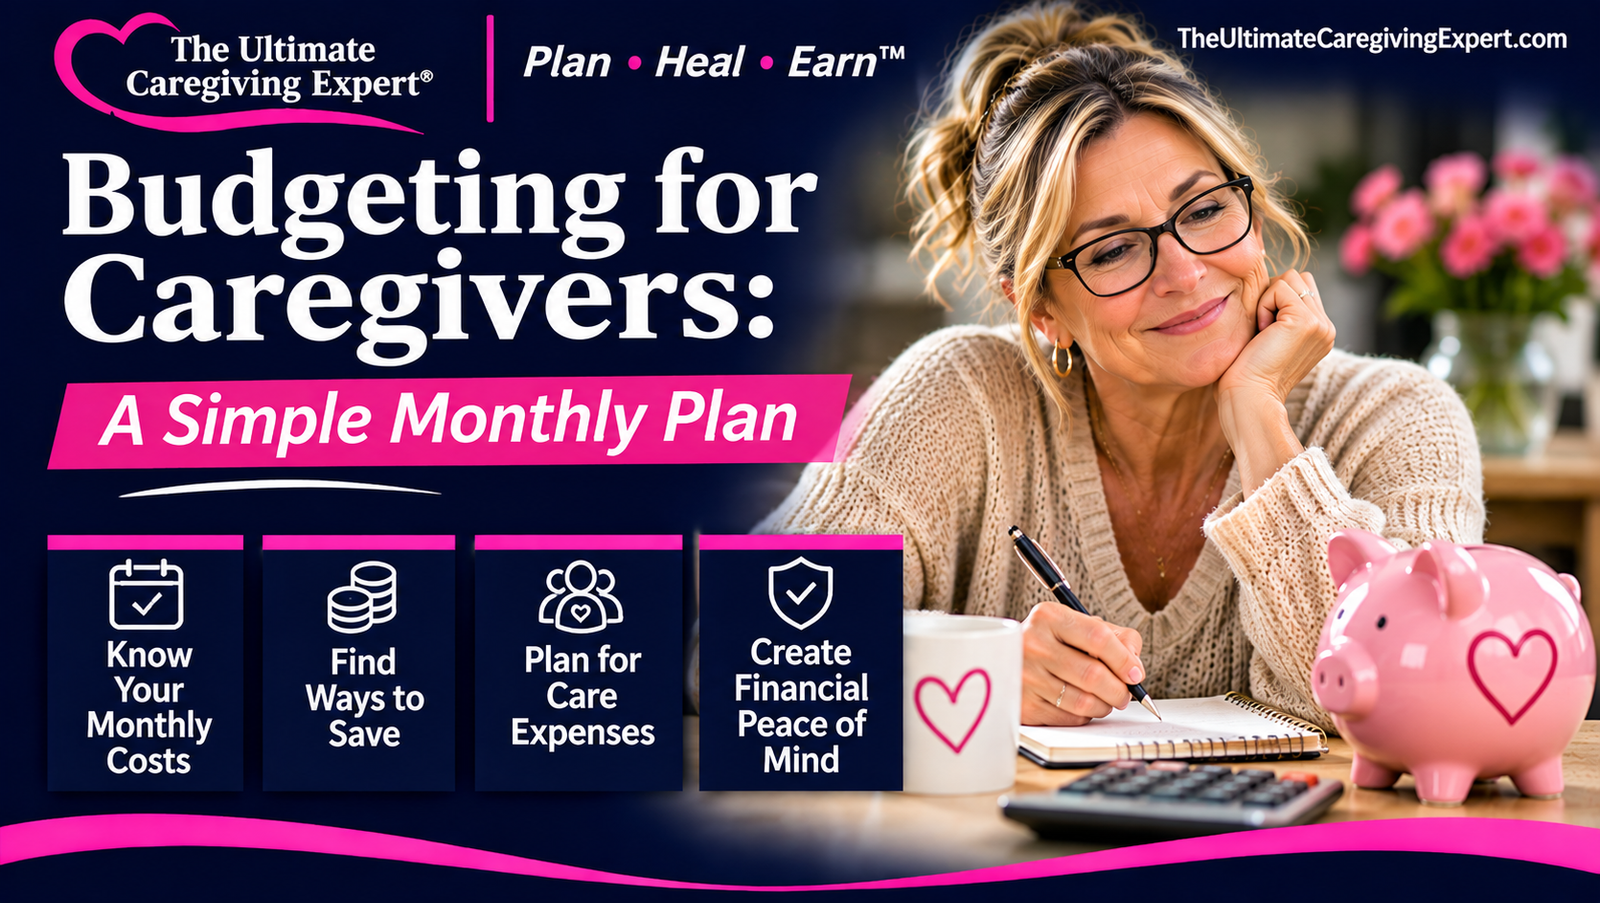
Budgeting for Caregivers
If caregiving is quietly draining your bank account, you are not imagining it. Family caregivers now spend an average of $11,508 a year of their own money on care, according to the 2026 AARP Caregiving Out of Pocket Costs Study. That is almost 60 percent more than five years ago.
I have been on both sides of this. I ran a home care agency for more than a decade, and I have cared for five members of my own family. The families who handle the money side best are not the ones with the most money. They are the ones with a plan they look at every month. This guide walks you through a simple monthly budget built for caregivers, one step at a time.
Why Budgeting for Caregivers Is Different
A normal household budget assumes your costs stay about the same each month. Caregiving does not work that way. A new prescription, a fall, a hospital stay, or a change in care needs can change your costs overnight.
The AARP study found that caregiving costs take up 31 percent of a caregiver’s household income on average. For caregivers earning under $40,000 a year, it is 76 percent. The biggest categories were housing and household expenses (42 percent of spending) and medical expenses (29 percent).
That is why a caregiver budget needs three things a regular budget does not: a clear list of care costs, a plan for who pays for what, and a cushion for surprises.
Step 1: List Every Caregiving Cost for One Month
For the next 30 days, write down every dollar you spend because of caregiving. Keep a notebook or a note on your phone. Include the small things. They add up faster than you think.
- Housing and household: rent or mortgage help, utilities, groceries for your loved one, home repairs, safety changes like grab bars
- Medical: copays, prescriptions, over-the-counter medicines, medical equipment
- Supplies: incontinence products, gloves, wipes, skin care, nutrition drinks
- Transportation: gas, parking at appointments, rides, car repairs from extra driving
- Paid help: home care aides, adult day programs, respite care
- Your own lost income: unpaid time off, reduced hours, or a job you left
That last line matters. Lost income is often the highest cost of caregiving, and most families never write it down.
Step 2: Sort Costs Into Fixed, Changing, and Surprise
Once you have a month of numbers, sort each cost into one of three groups.
- Fixed costs are the same every month, like a monthly aide schedule or a set prescription.
- Changing costs go up and down, like groceries, gas, and supplies.
- Surprise costs come without warning, like an emergency room visit or a broken wheelchair.
Fixed and changing costs go into your monthly budget. Surprise costs are what your cushion is for in Step 4.
Step 3: Decide Who Pays for What
Many caregivers pay for things without anyone ever deciding they should. Over time, that leads to resentment and money trouble. Write down where each cost will come from.
- Your loved one’s own income and savings, such as Social Security, a pension, or retirement savings. In many families, this should be the first source.
- Siblings and other family members. Ask for a set monthly amount or ask each person to cover one category, like supplies or transportation.
- Programs and benefits your loved one may qualify for. More on this in Step 5.
- You, for whatever is left, with a limit you can live with.
Put the plan in writing and share it with your family. A simple written plan prevents most money arguments before they start.
Your Simple Monthly Caregiver Budget
Use this layout for each month. Fill in the amounts from Steps 1 and 3.
| Category | Planned | Actual | Who Pays |
|---|---|---|---|
| Housing and household | |||
| Medical and prescriptions | |||
| Supplies | |||
| Transportation | |||
| Paid help and respite | |||
| Care cushion savings | |||
| Total |
Step 4: Build a Small Care Cushion
A care cushion is money set aside only for surprise caregiving costs. Start small. Even $25 a week adds up to more than $1,000 in a year.
Keep it in a separate account if you can, so it does not get spent on everyday bills. When a surprise cost hits, you pay it from the cushion instead of a credit card. For more ideas, read my guide to building a backup income plan for caregivers.
Step 5: Check What Help You May Qualify For
Many caregivers pay for things that a program, a benefit, or a tax break could help cover. Rules change and vary by state, so check each one for your situation.
- Tax credits and deductions. Some caregivers can claim a dependent or deduct medical costs. See my guide to caregiver tax credits and deductions.
- Paid family caregiver programs. Some states and Medicaid programs pay family members to provide care. See family caregiver compensation programs by state.
- Your local Area Agency on Aging. These offices can point you to respite care, meal programs, and other local help, often at low or no cost.
Step 6: Protect Your Own Income
The hardest budget problem for most caregivers is not spending. It is income that shrinks because caregiving takes your time. Before you cut back at work, talk with your employer about flexible hours or leave. Then look at ways to earn around your caregiving schedule.
I created The Caregiver’s Cashflow Plan for exactly this. It is a 30-day workbook that helps you turn the skills you already use every day into flexible income from home, built around your caregiving schedule. It is $27, and you can start today.
Step 7: Review Your Budget Once a Month
Pick one day each month and give it 15 minutes. Compare what you planned with what you actually spent. Adjust next month’s plan, update your family on any changes, and add to your cushion if you can.
Care needs change. Your budget should change with them. A short monthly review keeps small problems from turning into a crisis.
Budgeting for Caregivers FAQs
How much does family caregiving cost each year?
The 2026 AARP study found family caregivers spend an average of $11,508 a year of their own money on care. Your costs may be higher or lower depending on your loved one’s needs and where you live.
Should I use my own savings to pay for a parent’s care?
Start with your loved one’s own income and savings, and ask other family members to share costs, before you use your own savings. Your retirement and financial safety matter too. A financial professional can help with your specific situation.
What is the highest hidden cost of caregiving?
For many caregivers, it is lost income from reduced hours or leaving a job. Read more about the hidden costs of family caregiving.
You Do Not Have to Figure This Out Alone
A caregiver budget is not about cutting every cost. It is about knowing where the money goes, sharing the load, and protecting your own future while you care for someone you love.
If you want a full system, The Complete Family Caregiver System gives you all three of my workbooks for $67: The Caregiver Plan to get organized, The Caregiver Reset to recover from burnout, and The Caregiver’s Cashflow Plan to rebuild your income.
This article is general information, not financial, legal, or tax advice. Please talk with a qualified professional about your situation.